Subscriber exclusive
Keep reading with a subscription
This story is for subscribers. Start for $1 a week, or read three free stories a month with a free account.
Subscribe for $1 a weekClosing costs often run thousands of dollars on top of your down payment. Here’s what each fee is and how to lower it.
This story is for subscribers. Start for $1 a week, or read three free stories a month with a free account.
Subscribe for $1 a week Real EstateInside the Plan to Turn Empty Downtown Offices Into 1,200 Apartments
 Real EstateSaving for a House Down Payment: A Realistic Plan
 Real EstateRenting vs. Buying: The Honest Math
 Real EstateFirst-Time Home Buyer Checklist
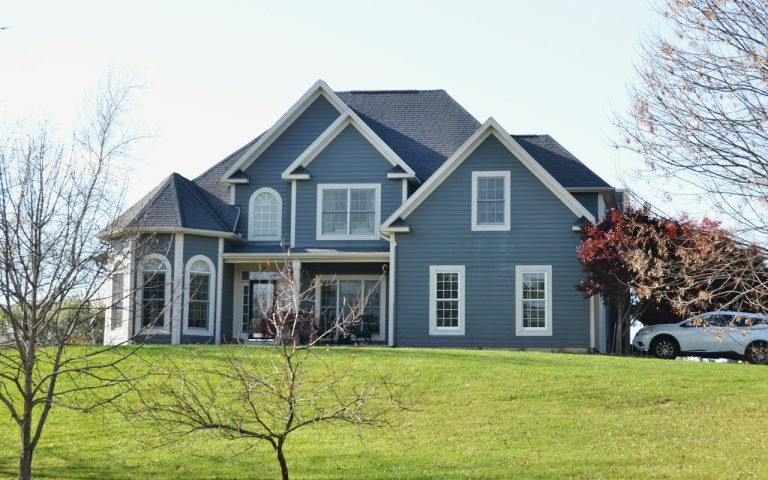 Real EstateWhat Your Mortgage Payment Really Includes
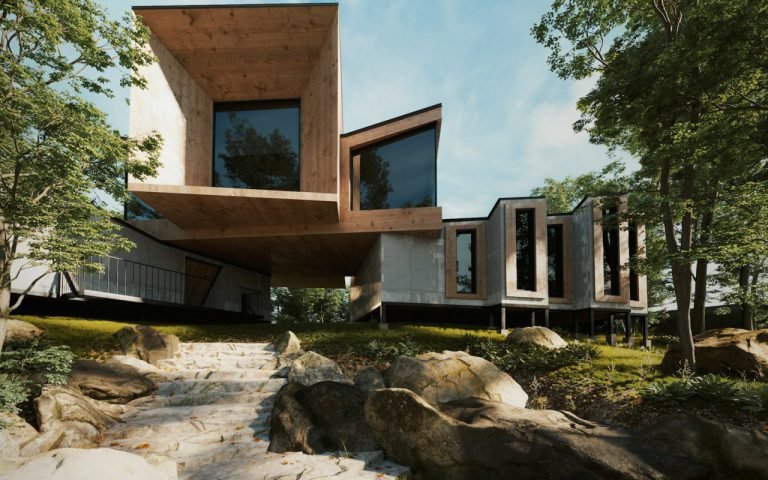 Real EstateA Cantilevered House Floats Over a Boulder Field in Northern California
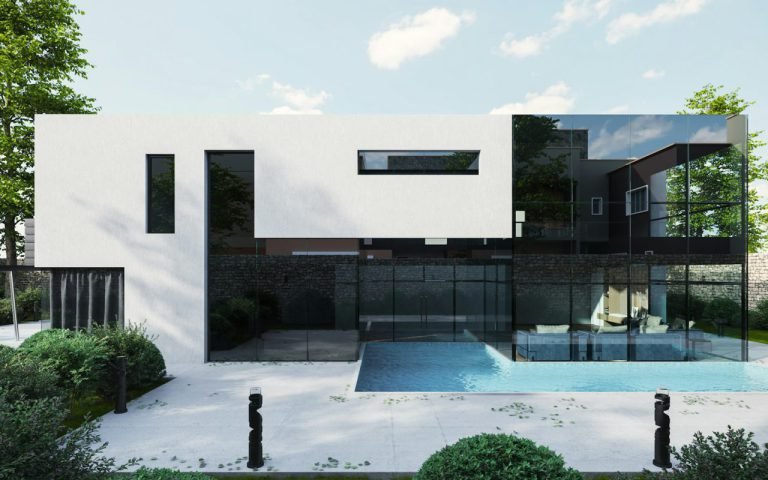 Real EstateThis Texas House Is Built Around a Courtyard Pool and a Single Oak
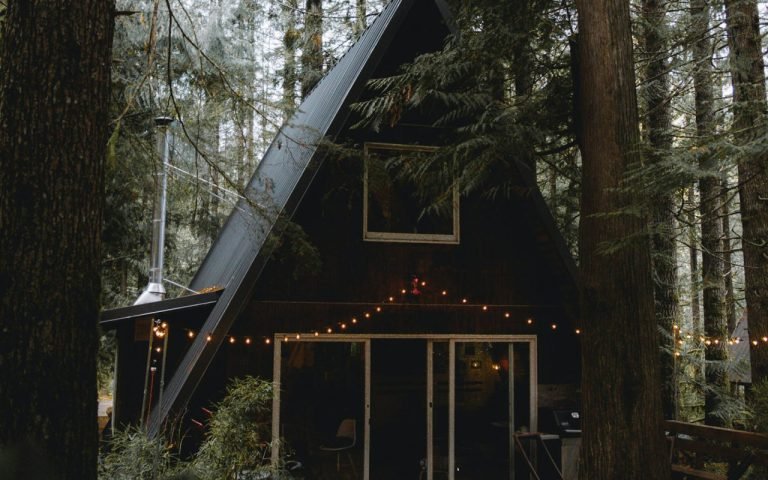 Real EstateA Black Timber A-Frame Brings Mid-Century Cabin Style Back to Oregon
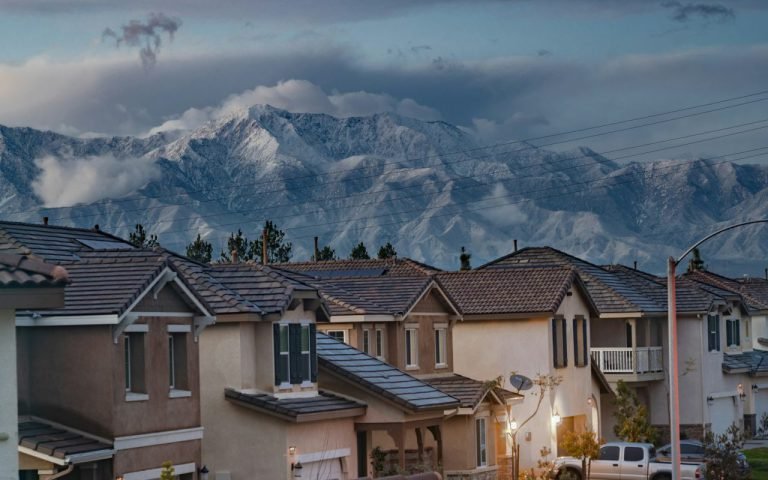 Real EstateFirst-Time Buyers Head Back to the Suburbs as Prices Ease and Commutes Shrink
Comparing three Loan Estimates saved us a little over $2,100. Wish I’d read this before our first offer.
The wire fraud warning is so important. Our title company warned us too and we almost didn’t take it seriously.